Sweet dreams for the chocolate industry
13:26
BY SEAN REYNAUD
While those consumption levels may seem like a lot, compared to the global per capita consumption of chocolate (0.9 kg per year), according to the EU’s Centre for the Promotion of Imports from developing countries, Poland still trails in per capita consumption of chocolate behind some European nations, with Switzerland at 10.5 kg and Germany at 9.3 kg per capita per year.
Even the UK tops Poland with almost 10 kg of chocolate consumed per year. But while Poles do not themselves consume as much chocolate as other countries, they are quite successful at manufacturing and exporting it.
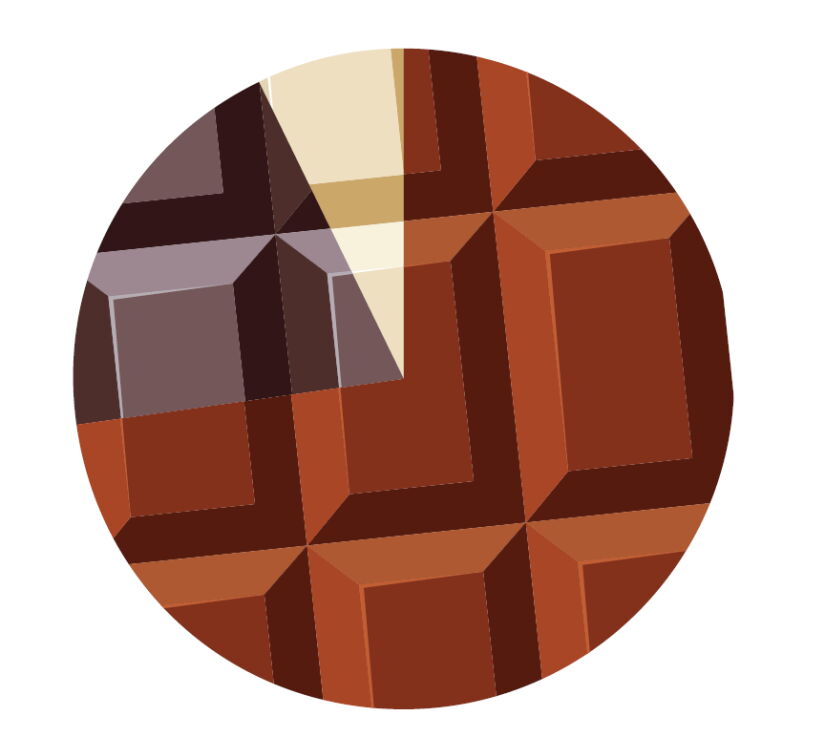
In Poland, 73% of individuals favor milk chocolate, while 20% prefer bitter or dark chocolate and 3.4% opt for white chocolate.
Poland on the podium
In April 2023, Poland’s chocolate exports reached 295 metric tons, making it the third largest exporter of chocolate in the EU, behind Germany, and the Netherlands, according to Eurostat data. And considering that 80% of chocolate production worldwide comes from six EU markets (even though Europe does not produce the key ingredient – cocoa beans), Poland is on the global chocolate podium.
The competitiveness of Polish products globally is in part driven by the weakness of the zloty. Which is why Poland’s share of the global market is estimated at just over 7%.
Europe produces, as well as consumes, the most chocolate, which is why Poland’s top importers of chocolate bars are: Germany, Belgium, France, the Netherlands, and Czechia. In the case of chocolate boxes (like Wedel’s flagship product Ptasie Mleczko), the group is only slightly different: Germany, Denmark, France, the Netherlands, and Romania.
German appetites
In both cases: chocolate bars and chocolate boxes, Germany is Poland’s top trading partner. In 2022, the western neighbor accounted for 18% of chocolate bars exports and as much as 32% of chocolate boxes.
The UK continues to be a major recipient of Poland’s chocolate exports, accounting for 15% of chocolate bars and 27% of chocolate boxes. Before the war, Russia and Ukraine were important trading partners too. Instead, Poland increased its shipments to Turkey and the US.
The pandemic and the war in Ukraine helped drive up costs for the chocolate industry due to supply chain issues or other changes in the macroeconomic environment. The frailty of the supply chain became evident as prices rose during the pandemic and grocery store shelves remained empty. As workers were affected by COVID-19, or were ordered into lockdowns, shipping ports experienced a critical shortage of truck drivers and workers.
Comfort buying
Panic buying took over in some countries, which led to a surge in sales of mainstream chocolates – those from popular brands, irrespective of their health benefits. Fear drove consumers to seek solace in “comfort foods.” This trend caused a temporary loss of market share for premium and specialty chocolates, particularly in the US.
However, as the pandemic waned, factors such as a growing preference for organic and sustainably sourced chocolate, attractive packaging solutions, enticing sensorial appeal, and the health benefits of dark chocolate helped reinvigorate the growth of the chocolate products market post-pandemic.
Roughly one-third of consumers increased their chocolate consumption as a result of COVID-19, according to Cargill’s new ChocoLogic study. Consumers chose chocolate flavors half the time in beverages, bakery, candy, ice cream, salty snacks, and snack/nutrition bars.
The inflation headache
As the pandemic subsided, the costs of raw materials continued to rise. Currently, the number one concern chocolate producers are now facing is the surging prices of key components, most notably sugar. Between March 2022 and March 2023, sugar prices shot up 83%, according to Statistics Poland (GUS) data. A kilogram of sugar cost on average PLN 6.32. Compared to the prices from September 2021, that’s a 124% increase.
Sugar prices are expected to continue rising in the short to medium term, according to Girish Chhimwal, a sugar analyst at S&P, because of weather risks plaguing top sugar producers. Unseasonal rainfall in India, a poor European beet crop, summer drought conditions last year, and OPEC+’s oil output cuts have created tough challenges.
Lower production was compounded by a poor European beet crop resulting from reduced acreage and a severe summer drought, as well as demand continuing to recover from the pandemic period. About 80% of global sugar production comes from sugarcane, while 20% is derived from beets. Add to this the 62% chance of El Niño from May to June of this year, which will affect rainfall in Asia. So, depending on the Asian monsoon rainfall, the sugar market could potentially become “very volatile” in the medium term.
Boxes are getting smaller
How do Polish chocolate producers deal with the staggering increases in prices? One way is to raise prices, but that has a very direct negative effect on sales, it turns out. Instead, chocolate manufacturers have started fiddling with the weight of the boxes. For instance, the world famous Ptasie Mleczko (cream marshmallows in chocolate) now weighs 340 grams, down from 360 grams last year. The size of the box has in fact been reduced multiple times over the years: it weighed 380 grams only five years ago, and a round 500 grams back in the 1990s.
When asked how consumers have taken to the even smaller box weight, the Wedel press office stated, as quoted by Portal Spożywczy: “We verified whether a reduction from 360 grams to 430 grams was possible through consumer research. While keeping the key elements: taste, shape, and number of marshmallows unchanged, we managed to optimize the cost of the product. Keeping with the previous weight would otherwise result in a price increase.”
Poised to grow?
Despite the challenges posed by increasing food prices, production costs, and supply chain disruptions, according to the Dun and Bradstreet corporation, the chocolate market in Poland is expected to grow by 5% in 2023.
Additionally, the immediate effects of environmental pressures on cacao growers have not yet reached significant levels. Despite these pressures, the Polish chocolate confectionery market is estimated to be at almost PLN 8.5 billion, representing a 10% increase from the same period in the previous year.
Chocolate producers also expect to see growth, as evidenced by their investments. Wedel, one of the largest chocolate confectionery manufacturers in Poland, launched an expansion of its Warsaw factory in February and expects its completion in Q3 2024. In addition to expanding the production area, Wedel approved another investment to build a new R&D lab, increasing the investment budget by an additional PLN 20 million to PLN 200 million.
It is safe to say that the demand for chocolate will continue to rise and that Poland will continue to reap the benefits of its cost-effectiveness vis-a-vis the weakness of the zloty, at least in the short term. But as the cost of raw materials continues its upward trend, as weather volatility interrupts crop yields, labor costs continue to rise, and supply chains work to regain stability, the long-term outlook for chocolate appears murky. But reports from several sources, including MarketWatch, forecast a more bullish outcome for chocolate up to 2030, to reach $172.5 billion. If true, Poland looks well-positioned to reap the rewards of our collective chocolate obsession.